How to Buy Commercial Property in Tbilisi
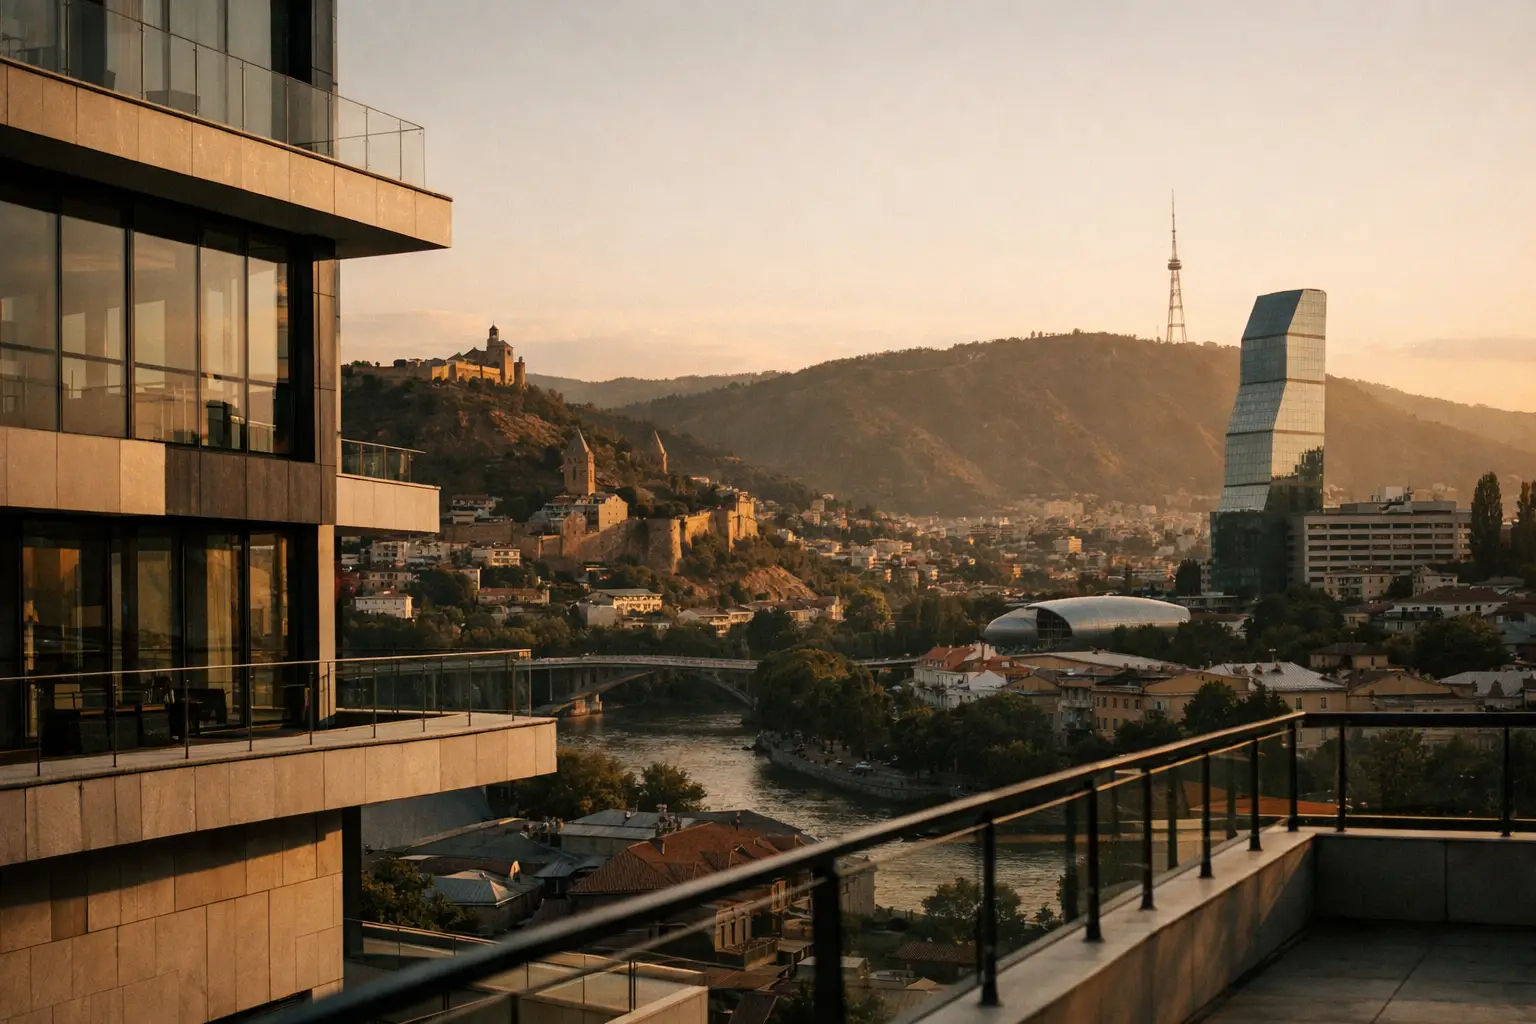
A ground-floor unit on a handsome Tbilisi street can still be a weak commercial purchase. I have seen spaces with wide windows, fresh renovation, and an attractive asking price that were difficult to lease because the entrance was hidden, the frontage sat behind parked cars, or people simply had no reason to walk on that side of the block.
If you plan to buy commercial property in Tbilisi remotely, the decision is less about finding a listing and more about answering a practical question: who will use this exact space, at what rent, and what happens if that tenant leaves? Commercial real estate does not forgive vague assumptions. A vacant unit can consume the return from several good months.
For a buyer working with $50,000 to $150,000, the best first move is to define the asset before looking at photos. Are you buying a small retail unit for lease income, an office for your own company, or a space you may eventually resell to another investor? These are different purchases, even when the square footage is similar.
Buy commercial property in Tbilisi by tenant, not brochure
The right property starts with the likely tenant. A clean 55-square-meter street unit is not automatically better than an 85-square-meter office on an upper floor. The smaller unit may have a more reliable leasing case if it is visible from the sidewalk, easy to enter, and placed near services people use every week. The office may be stronger if it has a practical layout, reliable elevator access, and sits near the businesses that need it.
Start with a tenant category, then test the premises against that category. For retail, look at daily pedestrian movement, storefront visibility, signage position, and whether a passerby can understand the entrance in two seconds. For offices, check the route from street to door, reception or lobby condition, parking arrangements, elevator capacity, and the quality of common areas. A tenant rents the full arrival experience, not just the room inside.
In central streets around Rustaveli, Chavchavadze Avenue, Pekini Avenue, Aghmashenebeli Avenue, and Marjanishvili, asking prices can reflect the address more than the unit's actual leasing strength. A location one block away from the active pedestrian line may trade at a discount for a reason. That reason can be temporary construction work, but it can also be permanent: weak visibility, a confusing approach, or no natural foot traffic outside working hours.
The first floor needs careful wording. In some buildings, “first floor” means one flight above street level. For a service business or retail tenant, that distinction matters. A true ground-floor entrance is usually easier to explain to a customer. An elevated first-floor space can work, but it needs another advantage such as a recognizable building, direct street-facing windows, or a tenant that does not depend on spontaneous walk-ins.
Read the street at three different times
A broker's daytime viewing is not enough. Commercial demand changes with the hour. A street that looks active at 1 p.m. may become empty after offices close. Another street may be quiet during the day and useful in the evening because residents, hotels, and visitors pass through it.
For each serious unit, assess the street on a weekday morning, weekday evening, and weekend. You are not looking for an abstract impression that the neighborhood is “busy.” You are looking for the right people. Office workers are useful for some tenants. Residents matter for others. Tourists can help, but their presence may be seasonal and their route can shift quickly.
Also stand across the road. Can you see the storefront from the normal walking path? Is the facade broken by trees, parked vehicles, street kiosks, or a bus stop? Is the entrance next to a dark passage, a service gate, or a building lobby that makes the unit feel private? These details are easy to miss in listing photos and hard to fix after purchase.
There is a real trade-off here. The most visible street-facing space often costs more and may offer less immediate yield at the seller's price. The less obvious unit may produce better numbers, but only if there is a credible reason a tenant will choose it. Cheap empty space is not a bargain just because it is in a known neighborhood.
The lease is the property’s operating history
If the premises are already leased, do not treat the stated rent as proof of income. Read how the lease works in practice. Check the remaining term, payment timing, deposit, rent increases, tenant obligations, notice period, and whether the tenant has a break option. A high monthly rent is less useful if the tenant can leave shortly after you close.
Ask for evidence of actual payment history where available, not just a stated agreement. Then consider the tenant's business model. Does it appear stable enough to remain in that unit? Is the rent proportionate to what the location can support? Would a replacement tenant accept similar terms if the current one leaves?
An occupied unit may reduce the work required at the start, but it can limit flexibility. You may inherit a tenant paying below current market expectations, or a tenant relationship that needs careful handling. A vacant unit gives you freedom to set the next lease, renovate, or reposition the premises, but it also gives you immediate carrying costs and an uncertain leasing timeline.
For a remote buyer, I prefer to calculate the property twice: once using the current rent, and once assuming a period without rent followed by a more conservative replacement rent. If the purchase only makes sense under the best-case version, it is not yet a sound decision.
Calculate the return after the unglamorous costs
Commercial return is not the advertised annual rent divided by the purchase price. That simple percentage leaves out the costs that become very visible once a tenant moves out.
At minimum, allow for vacancy, repairs between tenants, common-area charges where applicable, property insurance, accounting or administration, marketing for a new tenant, and management if you are abroad. If the unit needs a refresh, budget for the period when work is happening and no rent is coming in. A painted wall and new lighting may be enough in one office. Another space may need a more serious redesign before it is competitive.
The $50,000 to $150,000 range can be workable in Tbilisi, but it calls for discipline. At the lower end, buyers often face a choice between smaller space, a less central position, or a unit that needs attention. At the higher end, there may be more choice, but not necessarily a better deal. A larger unit has a narrower tenant pool and can take longer to re-lease. Size should match local demand, not just the budget available.
Be skeptical of gross-yield language. The useful number is the cash you expect to retain through an ordinary year, with an allowance for the periods that are not ordinary. No one can honestly promise a fixed result because tenant demand, rent levels, and resale conditions can change.
Inspect the building, not only the unit
A commercial unit relies on the building around it. An attractive office interior loses value when the lobby is neglected, elevators are unreliable, or access becomes difficult for visitors. A retail facade cannot fully compensate for poor drainage, damaged pavement, or a neighboring vacant frontage that makes the block look abandoned.
During an inspection, I look at the route from car or sidewalk to the door, the condition of the common areas, natural light, ceiling height, windows, noise, visible moisture, and the practical layout of walls and columns. I also look at neighboring occupiers. They affect how a future tenant sees the address.
One risk deserves direct attention: older buildings can hide expensive maintenance needs behind a recently renovated unit. Fresh flooring does not tell you much about water ingress, window condition, shared systems, or the state of the entrance. A buyer should not confuse cosmetic work with a durable commercial asset.
Decide your exit before you negotiate
Commercial property is easier to buy than to sell quickly. Your eventual buyer may be an investor seeking rent, an owner-occupier, or a local business. Each group values different things. An investor wants a credible lease and manageable costs. An owner-occupier may care more about layout, access, and the ability to adapt the space.
That is why highly specialized layouts can be risky. They may suit the current user perfectly while narrowing the next tenant and buyer pool. Flexible rectangular spaces with understandable access are usually easier to explain later, even if they look less dramatic in photographs.
Before making an offer, set your non-negotiables: the maximum all-in budget, the minimum rental scenario you can accept, the maximum vacant period you can carry, and the reason a future buyer would want the unit. Negotiation becomes clearer when these limits are decided in advance. The aim is not to win a discount from the asking price. It is to avoid paying for a story the property cannot support.
If you are considering a commercial unit in Tbilisi, send your budget, intended use, preferred holding period, and whether you need income from day one to Telegram @ShalinAE. I will turn that into a short task and assess the options against the street, tenant, lease, and exit case.